Sequence matters more than speed. Homeowners lose money after a storm in two ways: waiting too long, and doing the right things in the wrong order — permanent repairs before anyone documented the damage, a signature before anyone read the contract.
- 1. Wait for the all-clear, and stay off the roof. A wet, debris-covered roof with hidden soft decking is how storm injuries happen. Assess from the ground, from windows, and from inside the attic with a flashlight.
- 2. Contain water inside first. If water is coming in, the priority is the interior — buckets, plastic over furniture, pulling up wet rugs, cutting power to any circuit near water intrusion. Water sitting in a ceiling for three days turns a roof claim into a mold and drywall claim.
- 3. Photograph everything before you touch anything. Wide shots of the house from all four sides, close-ups of every damaged area, the interior stains, the debris on the ground, the fallen limb, the ceiling. Video walking the property narrating what you see. Leave the timestamps on.
- 4. Notify your carrier and get a claim number. Do it in the first day or two, in writing where you can, and note the date and time. The claim number is what every later conversation hangs on.
- 5. Get emergency dry-in — tarp or temporary patch — not permanent repairs. Your policy generally expects you to prevent further damage, and further damage you allowed can be argued about. Temporary protection is the right move; a brand-new roof installed before anyone inspected is not.
- 6. Keep every receipt, and keep the removed material. Tarps, plywood, a generator, a hotel night, the emergency dry-in invoice. Photograph the torn shingles or cracked tile that came off before any of it goes to the dump.
- 7. Get an independent assessment from a licensed roofing contractor before the adjuster comes. Not to argue — to know. Walking into an adjuster's inspection already understanding what failed and why is the difference between a conversation and a hope.
We inspect storm damage across Palm Beach County at no charge, and we'll tell you honestly when what you have is a repair rather than a replacement. Call (561) 779-3213.
If you searched for a roofer for a hurricane damage insurance claim in Palm Beach County, here is exactly what that work looks like: what an adjuster is actually checking for on the roof, how a licensed contractor's estimate differs from a public adjuster's report, and the realistic order of events from the day you file to the day the roof is fixed.
What an insurance adjuster looks for on a roof claim. An adjuster inspecting storm damage is generally working through the same questions: does the damage pattern match a wind or storm event rather than ordinary age and wear — creased, lifted, or missing coverings versus gradual granule loss and worn seals; is the decking underneath sound and properly fastened; is the damage confined to one slope or area, or spread across the whole roof; what does the roof's permit history and prior repair record show about its age and condition; and is there dated photo or video documentation tying the damage to the claimed date of loss. That is exactly why the pre-season "before" photos and the first-48-hours documentation covered above matter so much — they are the record an adjuster is looking for.
How a contractor's estimate differs from a public adjuster's report. A licensed roofing contractor's estimate is a construction document: a buildable, permittable line-item scope — materials, labor, disposal, and any code-upgrade items the 25% rule triggers — priced to actually execute a code-compliant repair or replacement. A public adjuster's report is a claims document aimed at the negotiated settlement between you and the carrier. They serve different purposes and often work together well; what a Certified Roofing Contractor adds is the technical, buildable scope from the deck up, independent of the settlement number.
Typical timeline from claim filing to repair. The paperwork side runs on the statutory clock described below: acknowledgment from the carrier within 14 days, a physical inspection within 30 days of your proof-of-loss statements if one is needed, and a pay-or-deny decision within 60 days of notice. Once the claim is resolved and a contractor scope is agreed, permitting time varies by jurisdiction and material lead time varies by product, and both happen before work starts. The physical repair itself is often the fastest part — many standard residential re-roofs are completed in a matter of days once permitted and material is on site, with tile and larger or more complex roofs taking longer.
If you typed "roofer for hurricane damage insurance claim Palm Beach County" into Google, here is the direct answer: a roofer for hurricane damage insurance claim Palm Beach County homeowners can rely on is a licensed Certified Roofing Contractor who inspects the roof and attic in person, photographs and dates every point of damage, pulls the property's permit history, and writes a buildable repair-or-replace scope tied to the Florida Building Code — not a drive-by estimate, and not a claims negotiation. That inspection covers the roof covering, the flashing and penetrations, the decking underneath, and the soffits, because an adjuster's decision usually turns on whether the damage pattern is fresh wind or storm damage versus ordinary wear, and a contractor's dated photo record and permit pull are exactly the documentation that answers that question. A licensed roofer's report carries weight with an adjuster for a simple reason: it comes from someone whose license — CCC1332751 — is on the line for the technical accuracy of the scope, independent of any settlement number.
Call (561) 779-3213 for the free inspection that starts that record, or see the walk-through above for what an adjuster is checking for and how a contractor's estimate differs from a public adjuster's report.
Plain English, no legal advice: your insurer decides your claim, and nobody can promise you approval. What a licensed Certified Roofing Contractor (CCC1332751) can do is hand you a clear, dated record of what the roof looks like, so the conversation with your carrier starts from facts instead of memory.
- Roof surface, section by section. Dated photos of each slope, ridge, hip and valley, with close-ups of anything creased, lifted, cracked or missing, and a sketch showing where each one sits.
- Flashing and penetrations. Vents, chimneys, skylights and wall transitions photographed separately, because water often enters there first.
- The attic side. Photos of the underside of the deck, staining and wet insulation, with the date, so interior damage is tied to the roof opening that caused it.
- Temporary protection. If water is coming in, we photograph before and after the tarp or dry-in, and keep the receipt.
- A written repair scope. A line-item estimate for a permitted, code-compliant repair or replacement, which you can hand to your carrier or adjuster.
We do not negotiate with your insurer, and we do not decide what is covered. Call (561) 779-3213 for the free inspection that starts that record.
A public adjuster negotiates the dollar amount of your claim with the carrier. A Certified Roofing Contractor does something different and just as important: we know what a roof assembly is required to do under the Florida Building Code, what a compliant repair actually takes to execute, and where an assembly failed against code — not against a policy form. Getting a Certified Roofing Contractor (CCC1332751) on the roof before or alongside the adjuster's visit gives your claim a technical scope written from the deck up, and a second set of eyes with no financial stake in the size of the settlement, only in the accuracy of the number.
This isn't an either-or. If you already have a public adjuster, our inspection and documentation feed theirs. If you don't, our inspection gives you an independent, technical basis to compare against whatever the carrier's own adjuster reports — which is the entire value of a disinterested set of eyes on the roof before you agree to anything.
Your OIR-B1-1802 wind-mitigation inspection records the features insurers price into your premium — roof-to-wall connections, roof deck attachment, roof geometry, opening protection, and a secondary water barrier. Those are also, not coincidentally, close to the features an adjuster is weighing when deciding whether wind exposed a pre-existing weakness or created new damage. Doing a wind-mitigation walk-through alongside a storm inspection gives you two records instead of one: a claim-specific damage report, and a baseline record of what your roof's protective features actually were going into the storm.
If your roof already had hurricane clips and a nailed-down deck, that record supports a wind-damage finding over a wear-and-tear one. If the walk-through turns up a missing secondary water barrier or an undocumented roof-to-wall connection, that's worth knowing before you rebuild — the replacement is your one chance to add it and start earning the premium credit going forward. That's why our free wind-mitigation & energy walk-through comes standard with every roofing estimate, storm-related or not: it costs you nothing, and going into a claim with your own baseline beats going in with only the carrier's version of your roof. Call (561) 779-3213 to book it.
Florida's insurance reforms shortened the clock dramatically, and this is the single most expensive thing homeowners still don't know. The windows below come from state law, not from any one carrier's policy:
- ⏱️ One year to give notice of a hurricane or windstorm claim. Under Florida Statute 627.70132, notice of a new claim must reach the insurer within one year of the date of loss — down from the three years many homeowners still believe they have. For a hurricane, the date of loss is the date of landfall as established by the National Hurricane Center, not the day you noticed the leak.
- 📄 Eighteen months for a supplemental or reopened claim. Measured from the date the insurer paid or denied the original claim. This is the window that matters when a tear-off reveals rotted decking nobody could have seen, or the first estimate turns out to be short.
- 📬 Fourteen days for the carrier to acknowledge you. Under Florida Statute 627.70131, the insurer must review and acknowledge a communication about your claim within 14 days unless it pays within that period, and must begin a reasonably necessary investigation within 14 days of receiving your proof-of-loss statements.
- 🔍 Thirty days to physically inspect. Where the carrier needs to inspect the property, the same statute requires it within 30 days of receiving your proof-of-loss statements.
- 💵 Sixty days to pay or deny. The insurer must pay or deny the claim, or a portion of it, within 60 days of receiving notice, absent factors beyond its control — and payment made late accrues statutory interest.
Two practical consequences. First: a leak you notice in March, from a storm that made landfall last September, is on last September's clock — and that clock may be nearly out. Second: if you're late but still inside the window, notice still beats silence. Missing the deadline entirely hands the carrier a complete defense no matter how plainly covered the damage was.
This page is general guidance from a licensed contractor. It is not legal or insurance advice, and we are neither attorneys nor public adjusters — a Florida roofing contractor cannot adjust or negotiate your claim, and any roofer who offers to is telling you something about how they operate. Your policy language governs your situation; confirm specifics with your agent, and if a claim is denied or underpaid, that is a conversation for a licensed public adjuster or an attorney.
Florida homeowners policies carry a separate, larger deductible for hurricane losses, and it surprises people at the worst possible moment. Under Florida Statute 627.701, residential carriers must offer a hurricane deductible of $500, or 2%, 5%, or 10% of your dwelling coverage — that is Coverage A, your rebuild limit, not your home's market value.
The percentage is where it bites. Purely as arithmetic: on a dwelling limit of $400,000, a 2% hurricane deductible is $8,000 and 5% is $20,000. Plenty of roof damage that feels catastrophic lands near or under that number — which is exactly why knowing your figure before storm season tells you whether a claim is even worth opening.
Two features of the law work in your favor:
- 📅 It applies once per calendar year. Once you have paid your full hurricane deductible on one storm, subsequent hurricanes in that same calendar year fall to your ordinary all-other-perils deductible. In a busy season that is real money.
- 🌀 The hurricane window is defined, not a judgment call. Hurricane coverage runs from the moment a hurricane watch or warning is issued for any part of Florida, through the duration of the storm, and for 72 hours after the last watch or warning ends. Damage outside that window is a windstorm claim under your regular deductible — a distinction worth checking rather than assuming.
Pull your declarations page now, find the hurricane deductible line, and do the multiplication before you need it. If the number startles you, that is a conversation to have with your agent in the spring — not in October.
Every named storm brings out-of-town crews into Palm Beach County. Some are legitimate contractors adding capacity where it is genuinely needed. Others are gone by winter, and the homeowner is left with an unpermitted roof, a compromised claim, and a phone number that rings in another state. The law gives you specific handholds:
- 🚫 Nobody can buy your claim with a gift. Under Florida Statute 489.147, a contractor may not offer a homeowner a rebate, gift, gift card, cash, coupon, or a waiver of your insurance deductible in exchange for letting them inspect your roof or for making a roof claim. Knowingly paying, waiving, or rebating your deductible is insurance fraud punishable as a third-degree felony. "We'll cover your deductible" is not a deal — it is a confession.
- 📃 Your roofing contract must carry the required notice. The same statute requires roof repair and replacement contracts to include that consumer notice, and a contract missing it may be voided by the homeowner within ten days of execution. Read the paper you are handed — what is absent from it tells you plenty.
- ✍️ You cannot sign your benefits over anymore — and should not be asked to. Under Florida Statute 627.7152(13), post-loss benefits under a residential property insurance policy may not be assigned, and an attempt to do so is void and unenforceable. Assignment-of-Benefits paperwork was the engine of the old abuse; if someone still puts an AOB in front of you, they are either years out of date or counting on you being.
- 🪪 Verify the license yourself, on the state's site. Roofing work requires a Florida certified or registered roofing contractor license — ours is CCC1332751, alongside Certified General Contractor CGC1528750, both searchable on DBPR. Ask for the license number rather than the truck logo, and check that the name on the license matches the name on the contract.
- 🏠 Ask where the warranty will be in three years. A written workmanship warranty is worth exactly as much as the company standing behind it. We are a local, state-licensed, insured, BBB A+ Accredited Business working out of Loxahatchee, and every job carries a written one-year workmanship warranty.
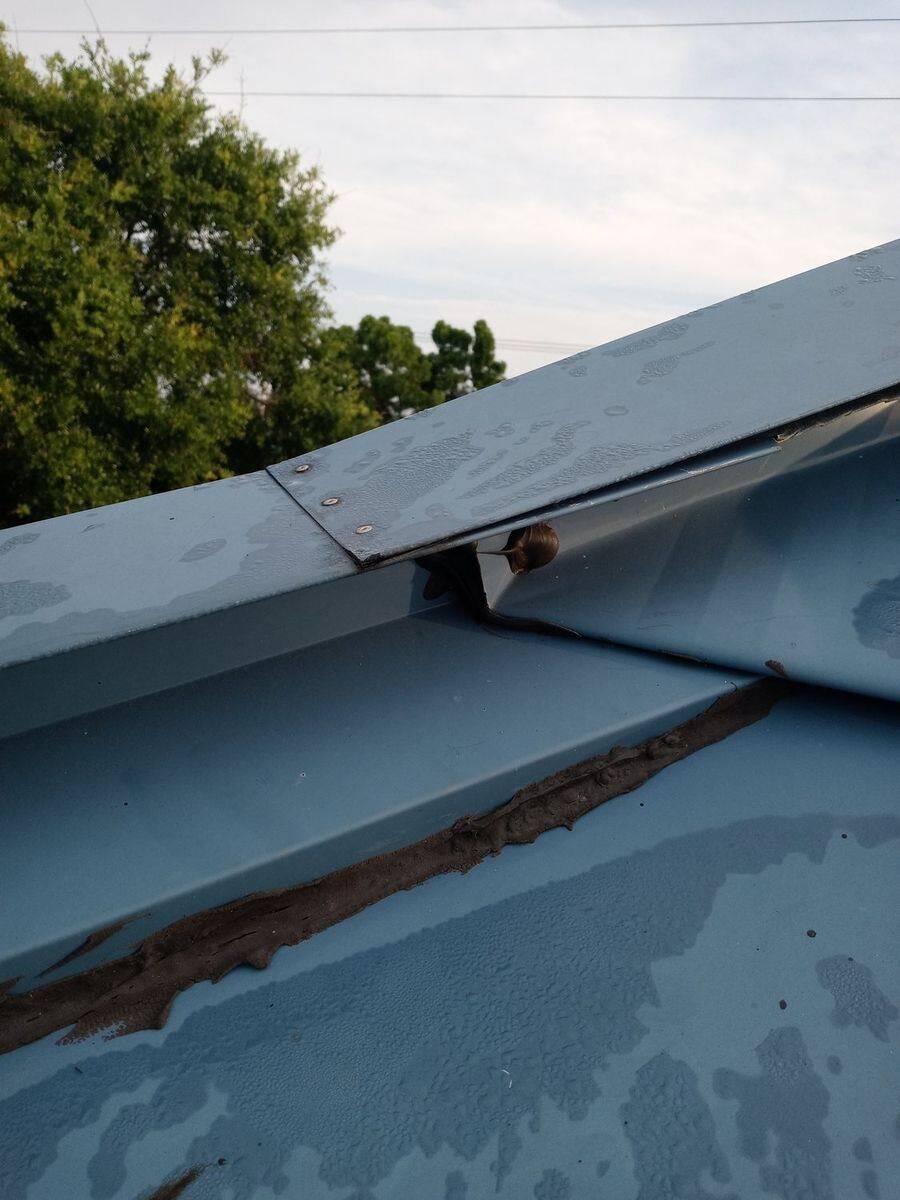
Whether the answer is a repair, a tile lift-and-relay, or a full replacement is not decided by damage alone — the Florida Building Code's 25% rule and your roof's permit date have a great deal to say about it, and the answer can swing thousands of dollars. That is covered in detail in the companion guide: Roof Age & Florida Insurance — the 15-year rule, the 25% rule, and the credits a new roof earns ↗
Not all storm damage announces itself. Wind lifts a shingle course, breaks the seal, and sets it back down looking normal. Tile slips a half inch. A soffit panel pops loose behind a gutter. Nothing leaks — until a routine afternoon thunderstorm two months later drives rain sideways into the gap, and a brown ring appears on a bedroom ceiling.
By then, three problems compound. The damage now looks like age and neglect rather than a storm event. Any documentation you would have gathered right afterward does not exist. And that one-year notice clock has been running the whole time from the day of landfall, not from the day the stain appeared.
So after any named storm that affected Palm Beach County — even one you sailed through — do two small things: walk the perimeter and photograph the roof from all four sides, and put your head in the attic on a dry day with a flashlight. If the roof looks untouched, you have just created a dated record proving it was fine, which is worth having in its own right. If something is off, you found it while it was still cheap and still provably storm-related.
An inspection after a near-miss is a genuinely good use of a free appointment. Call (561) 779-3213 and we will get on the roof so you do not have to.
We are a Florida Certified Roofing Contractor (CCC1332751) and Certified General Contractor (CGC1528750) based in Loxahatchee, working across Palm Beach County — West Palm Beach, Wellington, Royal Palm Beach, Jupiter, Palm Beach Gardens, Boynton Beach, Lake Worth, Greenacres, and the unincorporated Acreage. After a storm the sequence is the same every time:
- 🔎 A real inspection, on the roof and in the attic. Not a drive-by. We look at the covering, the flashing, the penetrations, the soffits, and the underside of the deck, because that is where the story of a leak is actually written.
- 📷 A documented photo set you keep. Dated, located, and organized, so you have your own record independent of anyone else's file.
- 🧾 An honest repair-or-replace call, plus your permit history. We pull the permit record before quoting, because it determines whether the code lets you repair. Sometimes the answer is a repair, and we will say so — that conversation is why people call us back years later.
- ⛑️ Emergency dry-in when the house needs protecting now. Temporary protection first, permanent work in the right order afterward.
- 📐 Permitted, inspected, code-compliant work. Installed to Florida Product Approval specification and carried through final inspection, with the deck nailing, straps, and sealed deck photographed before the covering goes on — the photo set your wind-mitigation inspector, your underwriter, and a future buyer will all ask for.
- 🌡️ The energy side, because the deck is open exactly once. A tear-off is the only moment to fix attic ventilation, radiant heat, and insulation gaps — and the owner is a certified energy rater, so those get specified rather than overlooked.
Palm Beach Gardens homeowners filing a hurricane roof claim are dealing with one more layer than a county resident. The City of Palm Beach Gardens runs its own Building Division at 10500 N Military Trail (561-799-4210), separate from unincorporated Palm Beach County, and that City office — not the county — is who a licensed roofing contractor pulls the permit from for both emergency dry-in and the permanent repair or replacement that follows. Confirming which office actually covers your parcel matters here specifically: Palm Beach Gardens' address lines run right up against the county line in several neighborhoods, and a permit filed with the wrong jurisdiction can stall a repair at exactly the moment your policy's notice clock is running.
Palm Beach Gardens is also unusual for how much of its housing stock sits inside a community that runs its own architectural review board on top of the City's permit process. PGA National, BallenIsles, Frenchman's Creek, Frenchman's Reserve, Mirasol, Evergrene, Alton and Avenir all require ARB sign-off on roof tile profile, color, or shingle color before the City will issue a permit for a full repair or re-roof — a step a county resident without an HOA never has to clear. The exception nearly every one of these boards makes is genuine emergency protection: temporary tarping or dry-in to stop active water intrusion is standard practice ahead of any board meeting, since the alternative is more interior damage while a board waits to convene. Still, notify your HOA or property manager that emergency work is happening, and get the ARB submittal moving the same week — product data, Florida Product Approval numbers, and color selections — so the permanent repair isn't waiting on a board that only meets monthly.
The insurance-claim mechanics are the same statewide law described above — the one-year notice deadline under Florida Statute 627.70132, the carrier's 14/30/60-day response clock under Florida Statute 627.70131 — but Palm Beach Gardens adds a wrinkle worth knowing before an adjuster ever shows up. A meaningful share of the city's original neighborhoods date to founder John D. MacArthur's 1960s and 70s garden-city plan, and those roofs are now well past the service life of their original covering. That makes the question every adjuster asks — fresh wind damage or ordinary age and wear — sharper here than in a newer subdivision, because a roof already near the end of its life gives a carrier more room to argue wear rather than storm. Dated "before" photos and a documented permit history matter more, not less, on an older Palm Beach Gardens roof.
No confirmed named roofing project of ours is in the project-to-city ledger for Palm Beach Gardens, and we won't invent one to fill the gap — the credential stack carries the claim instead: Certified Roofing Contractor license CCC1332751 and Certified General Contractor license CGC1528750, both state certifications letting us contract anywhere in Florida without additional local licensure, plus our documented commercial roof replacement at the Goodyear Building in nearby Jupiter. Bell Engineering holds a Palm Beach County Business Tax Receipt; Palm Beach Gardens sits inside that county, though no city-specific receipt is held there. See our Palm Beach Gardens roofing page ↗ for that city's full permitting and ARB detail.
Financing available through our partner Renew Financial's RenewPACE program — designed for energy and storm-protection upgrades like new roofs and impact windows. Ask us about eligibility. And since the same tear-off is your one chance to deal with attic heat and insulation, ask what the roof is costing you in cooling: see how these upgrades can also lower your energy bills ↗